Explore quantitative finance through student-written explainers, industry interviews and event insights.
The Merton jump-diffusion model extends GBM by adding sudden price jumps, capturing the discontinuous market repricing that continuous models cannot produce.
From random walks to Geometric Brownian Motion: an introduction to how quants model uncertainty and simulate changing asset prices.
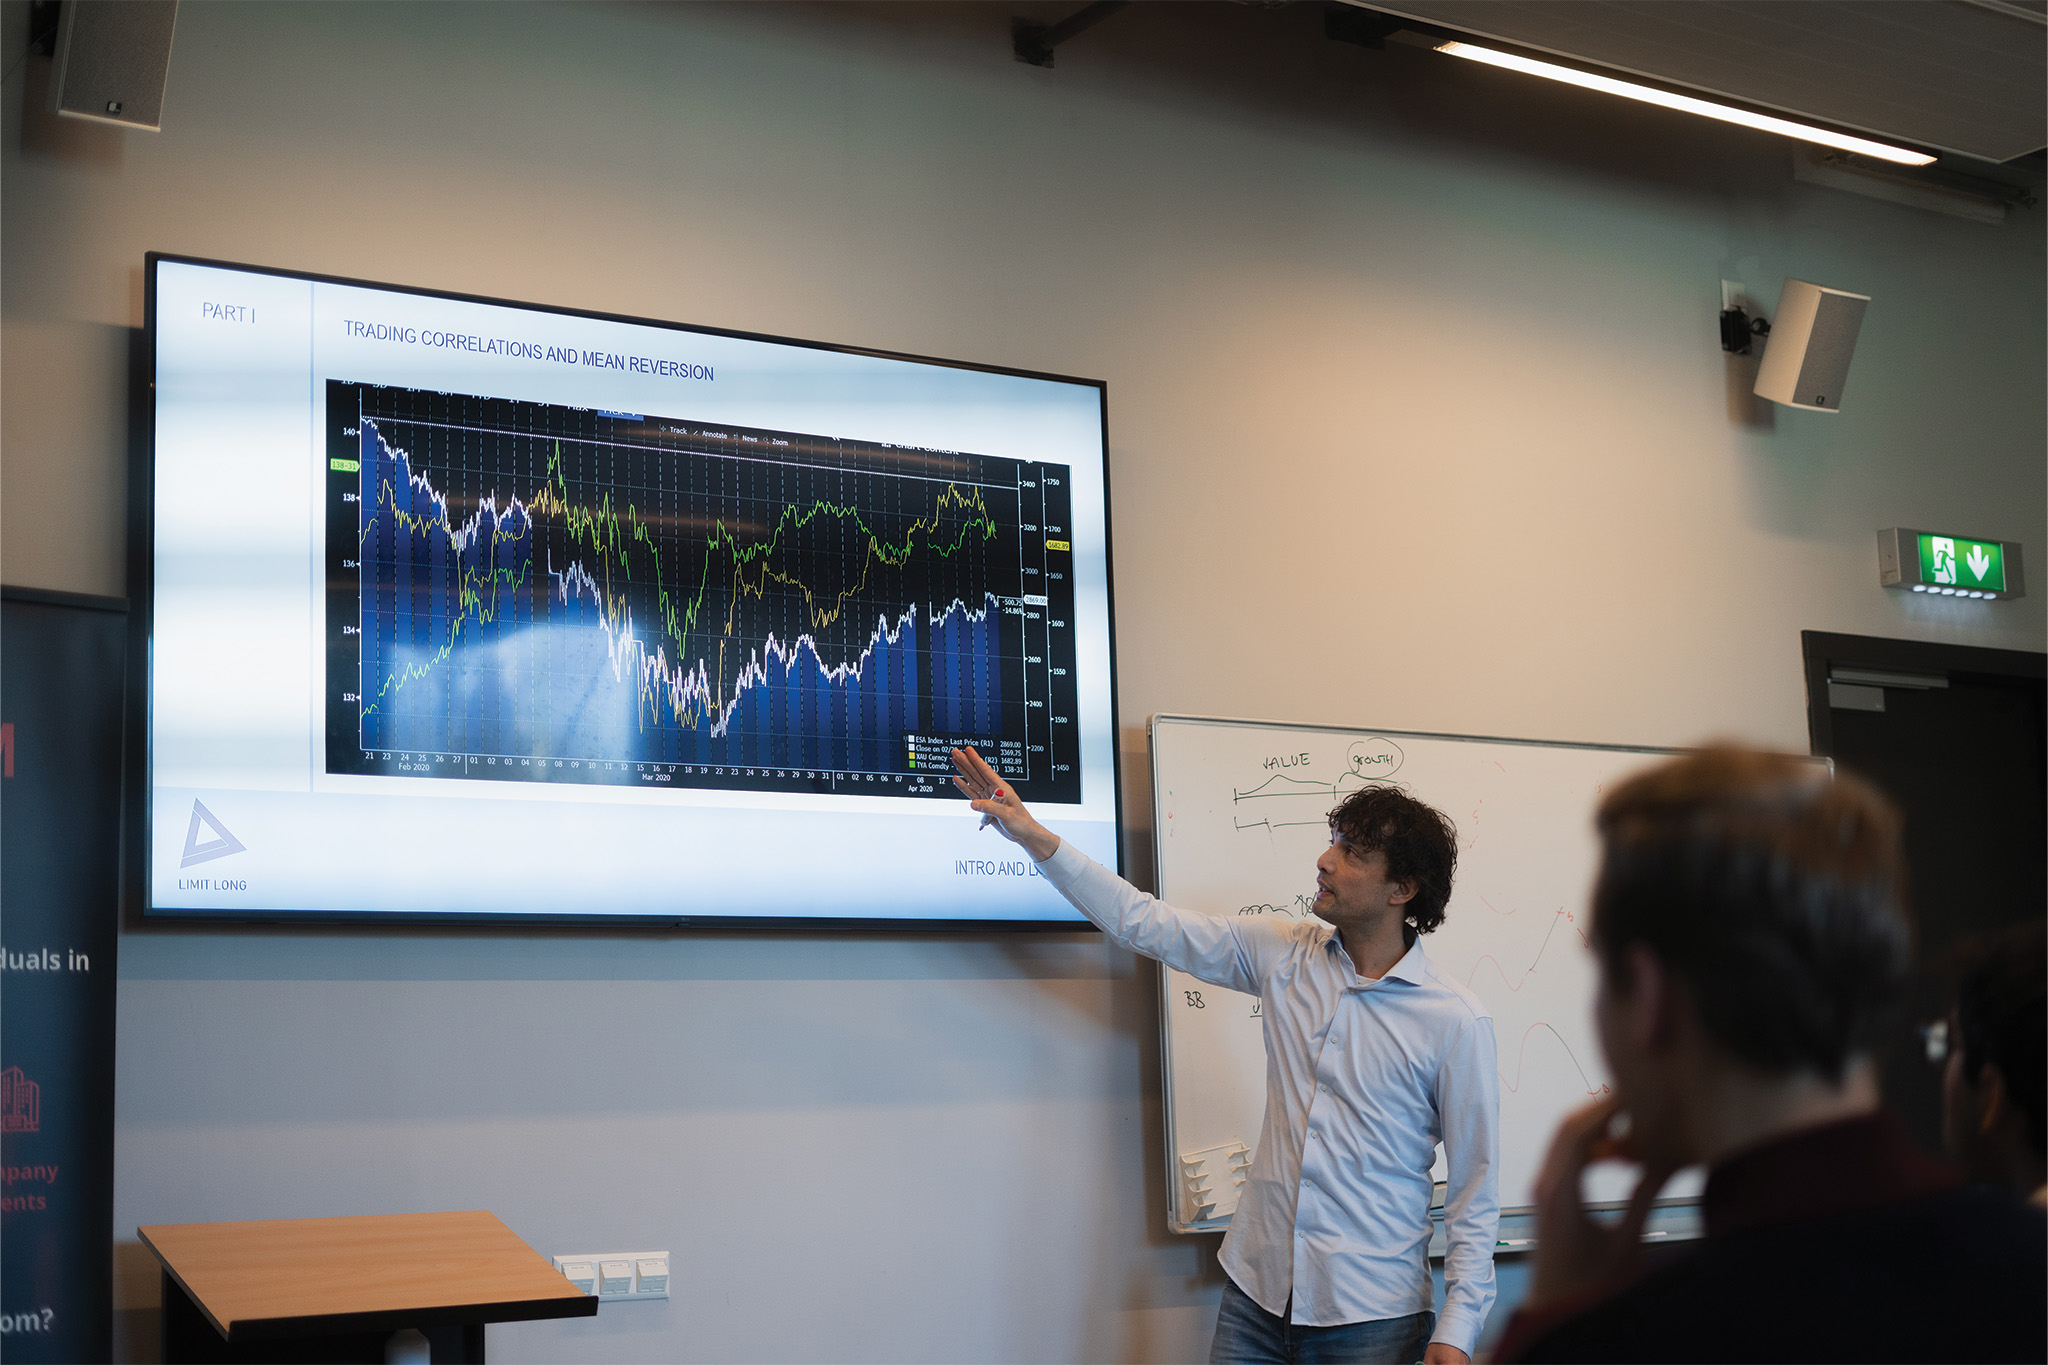
Vincent Vis, options trader and former market maker at Optiver and IMC Trading, broke down how markets actually work in practice — from trading philosophies and risk management to volatility and the moments when models break down, at AQS's recent Options Deep Dive event.
The Law of Large Numbers shows why small backtests deceive traders. Short-term results are unreliable due to noise, and extensive testing is essential.
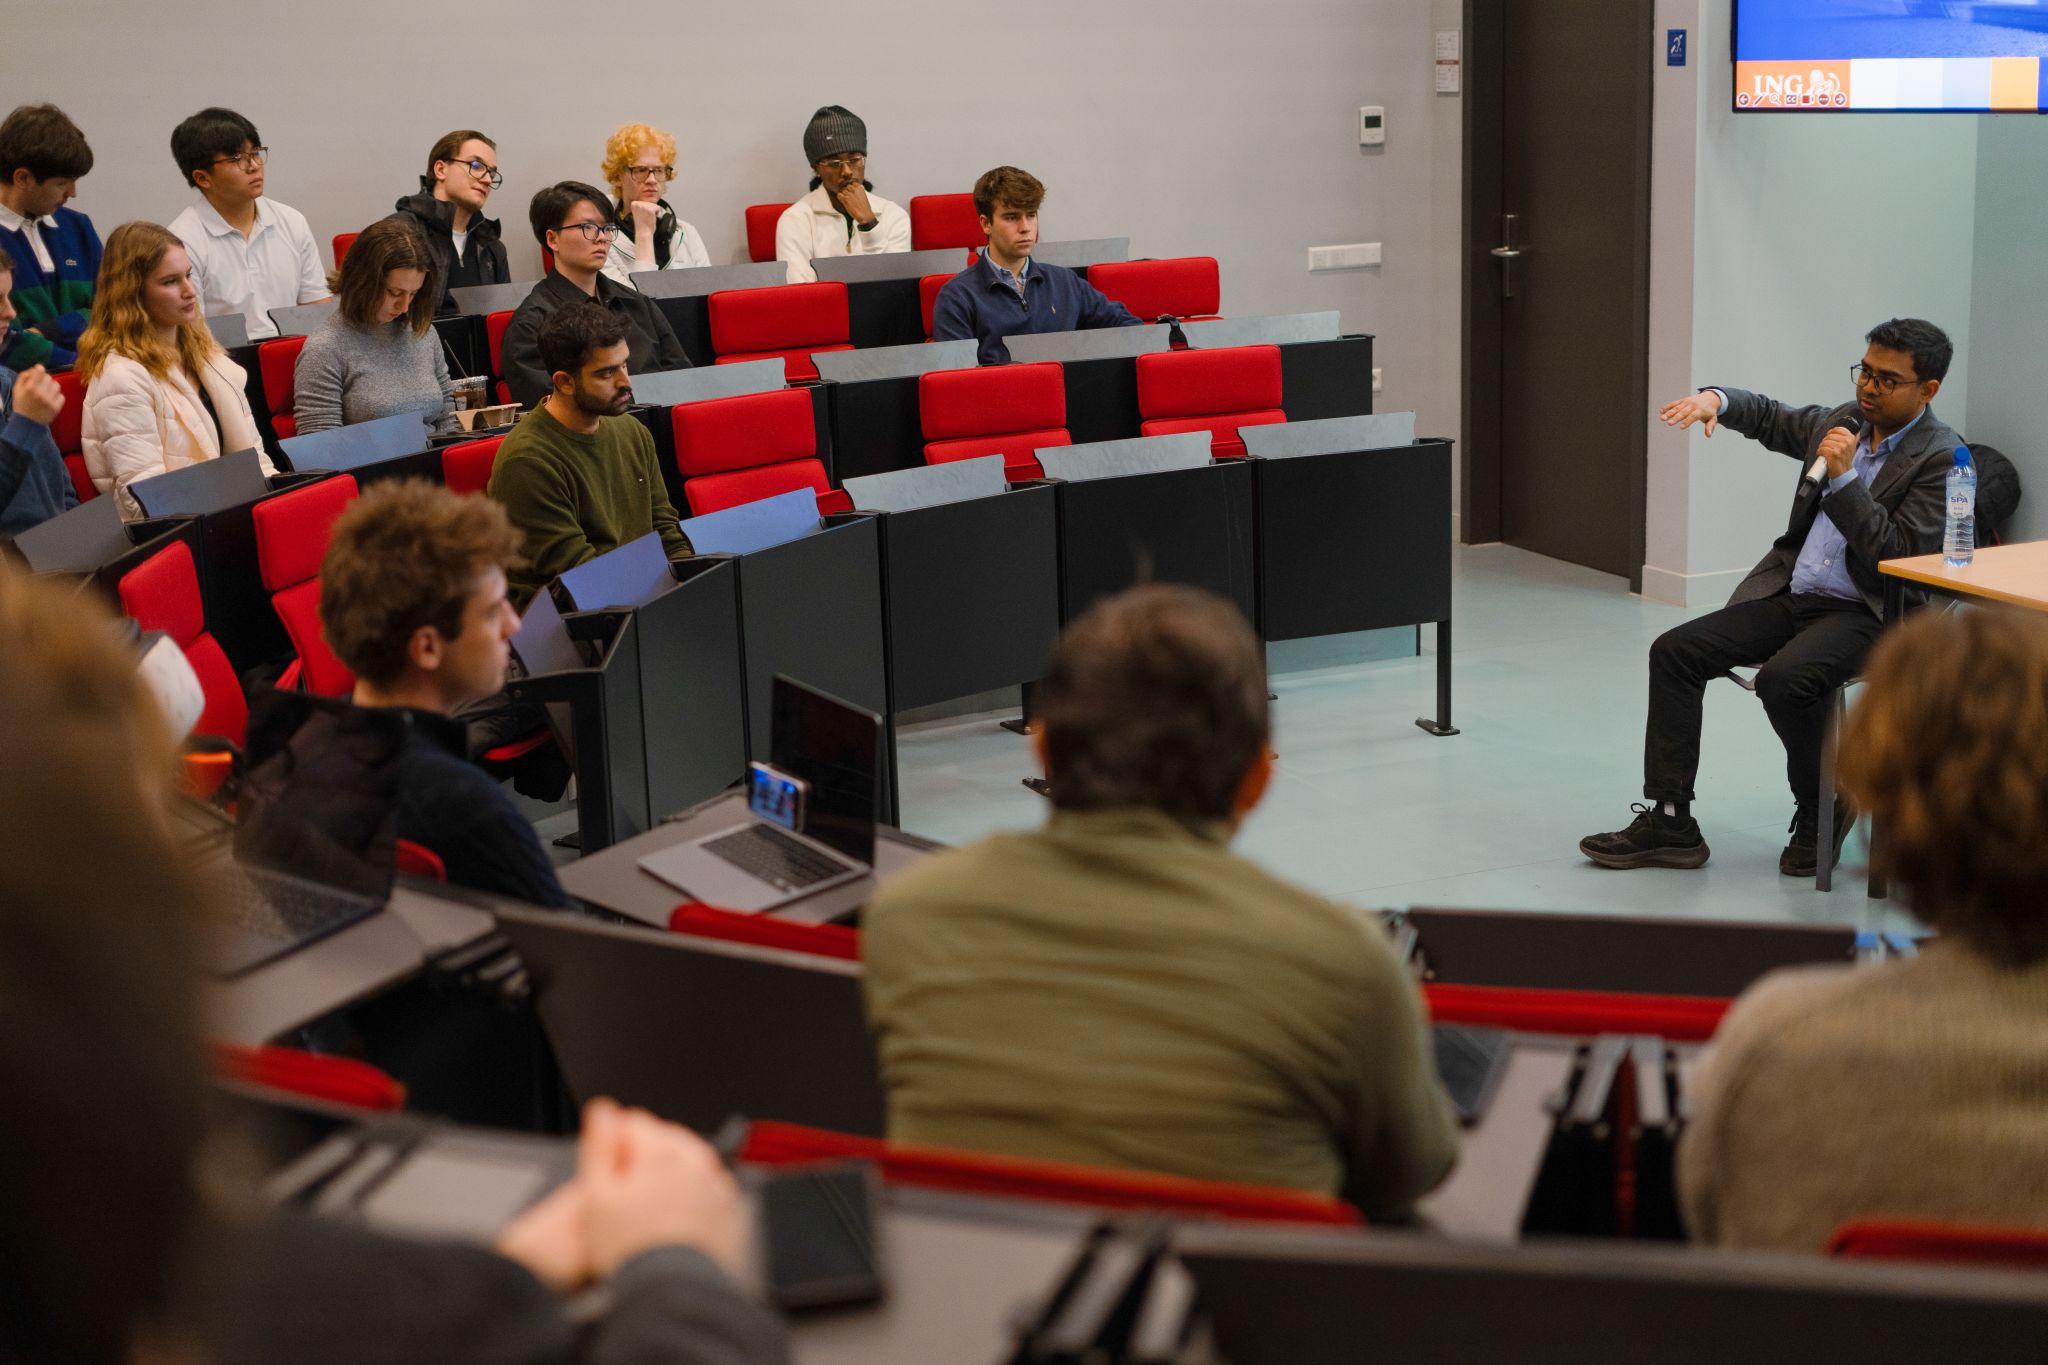
Sumit Sourabh, Director and xVA Quant Trader at ING, broke down what quant finance really looks like, from daily realities and career paths to hiring advice, at AQS's recent event.